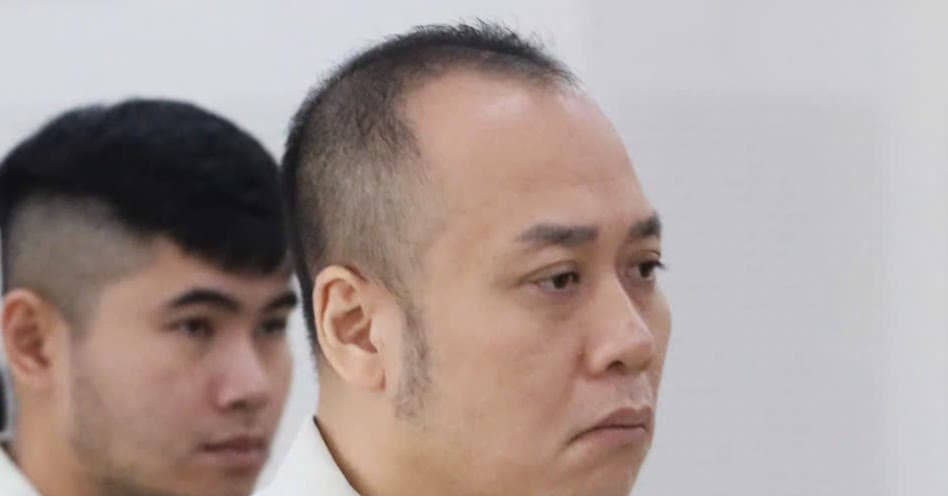
On the evening of September 24, the People's Court of Da Nang, Vietnam, delivered its verdict in the case of Công ty TNHH MTV Tư vấn đầu tư GFDI: general director Nguyễn Quang Hoàng, 38; finance director Nguyễn Đỗ Đạt, 34; head of the capital department Trần Thị Mỹ Hạnh, 34; head of the headquarters trading exchange Tô Hồng Trà, 35; and deputy head of the headquarters trading exchange Trần Thị Kiều Trang, 38, were all sentenced to life imprisonment for the crime of "fraudulent appropriation of property."
In his final statement, Nguyễn Quang Hoàng broke down in tears in court, apologized to the victims and relevant parties, and asked to be given a chance to return earlier to make amends for the consequences.
The indictment said that by 2023 the company was already losing money and had lost its ability to pay, yet Nguyễn Quang Hoàng instructed employees to release false information to the public and continue raising funds from clients. After the money came in, he used later investors' money to repay principal and interest to earlier lenders, to invest in international stocks, and to pay the company's operating expenses, rather than putting it into business operations as promised to clients at the outset. The indictment determined that Nguyễn Quang Hoàng appropriated more than 2,407 billion VND from 7108 victims (over 2.4 trillion VND). The other 4 defendants, knowing that the company was losing money and that the funds were not being used for the promised purposes, still took part and provided him with assistance.
During questioning at trial, multiple victims said that GFDI employees had introduced them to the high interest, which led them to borrow money to invest, and some even mobilized family members to pool money together. After the company could no longer pay, many families fell into hardship and their lives were thrown into disarray. The victims asked the court to impose severe sentences and order the defendants to compensate the money that had been appropriated.
Ms. B.T.L.L., born in 1990 and living in Gò Nổi commune, lost more than 700 million VND. After seeing GFDI employees post on social media promoting high interest rates, she borrowed money to invest 500 million VND and also got her mother to invest another 200 million VND. Up to now, she has not recovered a single dong of either principal or interest.
Even more heartbreaking, many GFDI employees were themselves victims. Ms. N.T.K.T., born in 1993 and living in Điện Bàn Đông ward, said that she herself was deceived, and because her mother and older sister trusted her, they also put money into the company; she asked that the salary and business income she had received be used to offset her compensation obligation. Ms. N.T.H.M., born in 1980 and living in An Hải ward, was a GFDI salesperson; she herself invested nearly 1 billion VND and also brought in relatives to invest.
The trial panel pointed out that the commissions and business fees received from GFDI by employees and related persons all came from the victims' money, and the relevant authorities would recover these sums to protect the victims' rights and interests.
For people making a living in Southeast Asia, saving money is not easy, and there are 2 things they fear most: first, that money kept in the bank earns only meager interest; second, that someone pounds their chest and says they can help you earn a little more. In the GFDI case, the most heartbreaking part was the chain of one "insider" after another: employees trusted the company, mothers and older sisters trusted their daughters and younger sisters, and relatives trusted relatives. That trust among acquaintances was turned by the scam into its handiest conveyor belt.
Scam-proof guide: How to spot high-interest wealth-management and high-interest deposit-gathering scams
1. How the scam reels people in step by step
According to a warning issued this July by the Economic Security Division of the Public Security Department of Vietnam's Hung Yen province, this is roughly how such "high-interest deposit" and "high-interest wealth management" scams operate:
● Impersonate employees of banks or finance companies, or create a website or app that looks very similar to a legitimate credit institution, to first gain trust;
● Solicit people with claims such as "risk-free," "withdraw your principal at any time," and "guaranteed high returns," promising annual interest of 18%–20%, or even higher;
● At the beginning, pay a small amount of interest on time to put you at ease, then induce you to invest larger sums of money, and then abscond with the funds;
● Ask you to transfer money into a personal account, or into an account that does not belong to a credit institution; induce you to click fake links or install apps from unknown sources, in order to obtain your online banking account and password, OTP verification code, and bank card information, and then transfer the money out of your account;
● Some also print and distribute fake flyers with QR codes; once scanned, they lead to a fake website, or display the scammer's phone number.
The GFDI case also illustrates another common structure: the company had long been losing money, and used the money of later entrants to pay the principal and interest of earlier entrants, robbing Peter to pay Paul, until it could no longer keep going.
2. The moment these warning signs appear, you should stop
● The interest rate is far higher than the general market level, yet they still confidently claim it is "risk-free."
● The fundraising or investment group or company has not obtained permission from the competent authorities.
● They ask you to transfer money into a personal account, or ask you to hand over your OTP or online banking password.
● The person promoting it to you is an acquaintance or an employee, with hefty commissions in hand: the court has already determined that the commissions received by GFDI employees came from victims' money and will be recovered. The extra money earned by "recruiting people" may ultimately have to be paid back.
3. There is only one legitimate path
The Vietnamese police's advice is straightforward: deposit money only in banks and credit institutions legally permitted to operate; use only the official channels of banks and credit institutions when handling transactions, and carefully verify websites and Apps.
4. What to do if you have already transferred the money
● If you notice anything suspicious, immediately report it to the nearest public security authority, or contact your bank and request timely handling.
● Keep your contracts, receipts, transfer vouchers, chat records, and the other party's promotional materials, and submit them together when reporting the case.
● Do not delay out of embarrassment, and do not "put in more money" in the hope of recovering your principal. Telling your family and friends about your experience is helping them avoid the next trap.
Money kept in a legitimate bank may earn a bit less interest, but it will not disappear overnight. Those unusually high interest rates are often not earned at all, but shifted from other people's principal, and sooner or later someone will have to pay the bill.