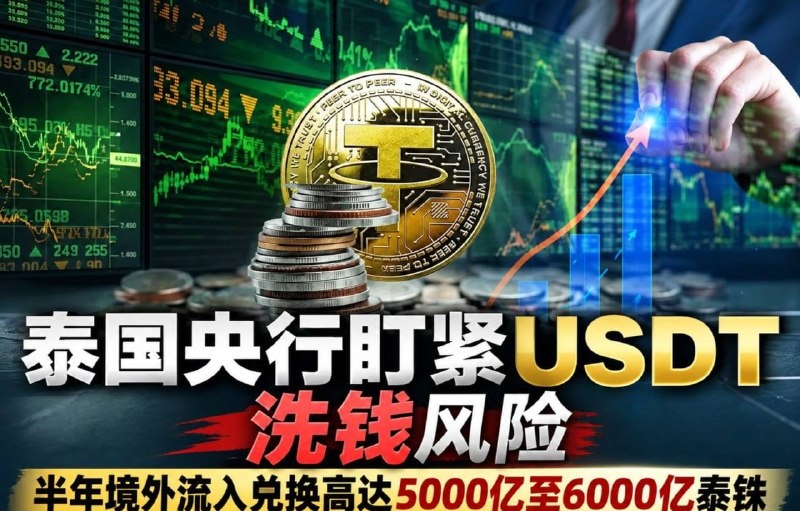
If you have been sitting down for coffee in Bangkok over the past few days, the talk of the town is what the central bank is up to. Bank of Thailand Governor Vithai has openly stated that authorities are tightening their grip on USDT, heavy cash moves, and gold shop counters. Simply put, they are determined to plug the loopholes fueling money laundering and illicit cross-border transfers.
The numbers on the central bank’s ledger explain why. Every six months, between 500 billion and 600 billion baht worth of offshore USDT is being cashed out into Thai baht. With sums that massive, stablecoins were bound to land straight in the crosshairs. People used to think moving funds on-chain kept them in the clear, but now all those street-level cash-out hubs are operating under the regulator’s watchful eye.
Throwing around large wads of cash and buying gold bars has gotten a lot harder, too. Ever since the threshold for strict checks kicked in on single-day withdrawals over 5 million baht, total monthly cash withdrawals across the board plunged from 100 billion baht down to 40 billion. It is the same story at the gold shops, where suspicious transactions collapsed from 20 billion baht to just 3 billion. According to local media, the central bank is even weighing a 0.1% tax on gold transactions—not to make money, but to force a paper trail and see exactly where all the funds are flowing.